Legally Defensible SDS Generation: A Smarter Approach to IR35 Compliance for UK Tech Businesses
Legally Defensible SDS Generation:
For UK IT, SaaS and technology businesses, engaging contractors through personal service companies can provide access to specialist skills without traditional permanent hiring.
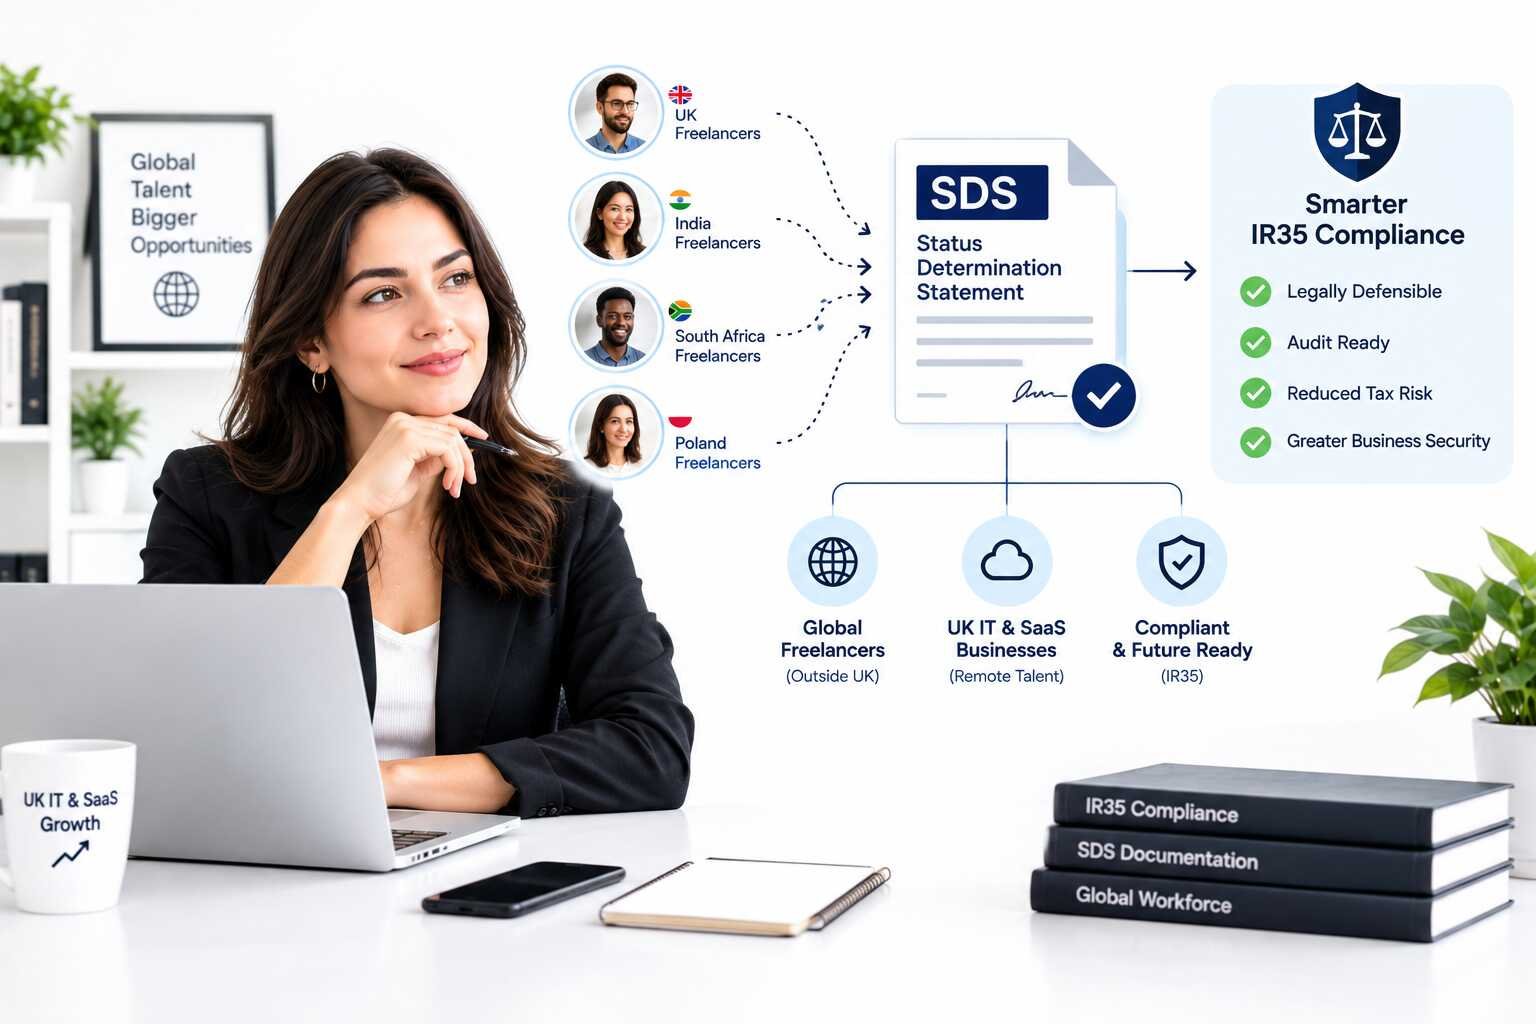
But under the UK’s off-payroll working rules (IR35), contractor engagement is not simply a procurement decision. For medium and large private-sector organisations within scope, the client is generally responsible for determining whether the rules apply and communicating that decision through a Status Determination Statement (SDS).
HMRC states that a valid SDS must contain the status decision, the reasons for reaching it and evidence that the client took reasonable care when making the determination.
For CFOs, finance directors and technology leaders, the challenge is therefore not just producing an SDS. It is creating a repeatable, documented and audit-ready determination process.
What Makes an SDS Legally Defensible?
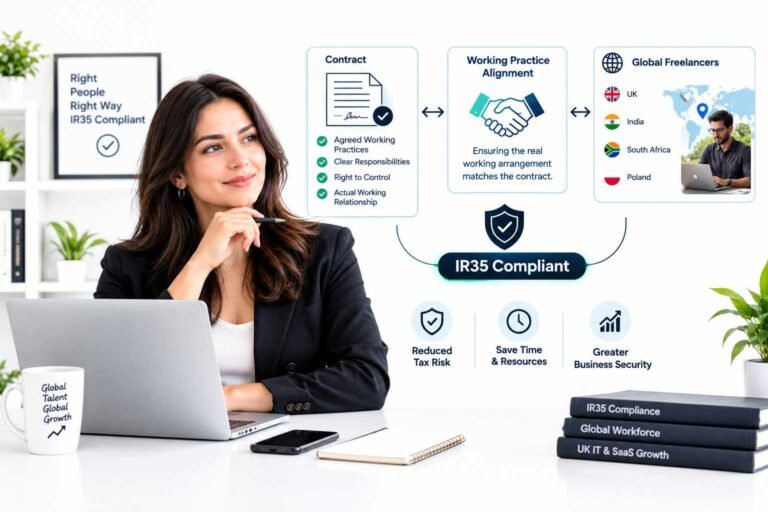
HMRC does not prescribe a single statutory format for an SDS. However, its guidance states that a valid SDS needs three core elements:
- The status decision — whether the worker would be an employee or office holder for tax purposes if engaged directly.
- Reasons for the decision — based on the relevant employment-status indicators.
- Reasonable care — the client must have taken reasonable care when reaching its conclusion.
This means a simple document stating “inside IR35” or “outside IR35” is not enough.
The determination needs to be supported by the facts of the particular engagement.
Why Blanket IR35 Decisions Create Risk?
One of the biggest weaknesses in contractor compliance is treating everyone in the same role identically.
HMRC guidance makes clear that clients should not simply classify all contractors as inside or outside the off-payroll rules regardless of their contractual terms and actual working arrangements.
Consider two software developers working for the same UK SaaS company.
One might have significant control over how the project is delivered, provide services independently and work on defined deliverables.
Another might work under close supervision, follow company processes and perform an ongoing role integrated into the organisation.
Although their job titles may be identical, the underlying facts could produce different employment-status considerations.
The key principle is simple: assess the engagement, not merely the job title.
What Should an Audit-Ready SDS Process Capture?
A robust process should connect the SDS to the evidence behind the determination.
For each engagement, consider maintaining records covering:
- Contractor and intermediary details
- Contractual terms
- Actual working practices
- Control and supervision
- Personal service and substitution
- Mutuality of obligation
- Financial risk
- Opportunity to profit
- Integration
- Provision of equipment
- Right to work elsewhere
- Relevant HMRC CEST output, where used
- Final status determination
- Reasons supporting the determination
- Date the determination was made
- Date the SDS was issued
- Worker and agency/contracting-party notification
- Any subsequent disagreement or review
HMRC says clients should keep detailed records of employment-status determinations, including the reasons for the determination and fees paid.
That documentation can become particularly valuable if HMRC later asks the business to demonstrate how its decisions were reached.
Automating SDS Generation Before Payment.
For a growing UK technology business, manually preparing every SDS can become difficult when contractor numbers increase.
A more controlled approach is to build SDS generation into the contractor onboarding and payment workflow:
Engagement data → Status assessment → Review → SDS generation → Contractor notification → Fee-payer notification → Payment
The objective is to ensure that the required status decision and supporting reasoning are completed before the relevant payment process proceeds, rather than trying to reconstruct the compliance record afterwards.
This can help finance and HR teams create a consistent audit trail while reducing repetitive administrative work.
However, automation should support the determination process rather than replace appropriate human oversight. HMRC states that even where a client subcontracts the determination or SDS production, the client remains responsible for reasonable care, accuracy and communicating the SDS.
Don’t Forget the Contractor and Fee-Payer.
An SDS is not simply an internal finance document.
Where the off-payroll rules apply, the client must communicate its determination and reasons to the worker and the relevant organisation it contracts with. In a labour supply chain, the SDS may need to pass through the chain to the fee-payer.
This makes workflow automation particularly useful.
A well-designed process can create a record showing:
Who was assessed → What was decided → Why it was decided → Who received the SDS → When it was issued → What happened afterwards
That is considerably more useful from an audit perspective than a collection of disconnected emails and spreadsheets.
What Happens If a Contractor Disagrees?
Contractors and deemed employers can challenge an SDS through the client-led disagreement process.
The client must consider the representations and respond within 45 calendar days of receiving the disagreement. If the original determination is maintained, the client must provide reasons; if it is changed, a new SDS must be issued with the applicable date.
For a business managing dozens or hundreds of contractors, maintaining a structured disagreement workflow can therefore be just as important as generating the original SDS.
Why CFOs Should Care About SDS Automation
IR35 compliance sits at the intersection of tax, finance, HR, procurement and legal risk.
An ineffective process can leave critical questions unanswered:
- Why was this contractor classified outside the rules?
- What evidence supported the decision?
- Was the determination based on actual working practices?
- Was the SDS issued to the required parties?
- Was the determination reviewed when circumstances changed?
- Can the business demonstrate that reasonable care was taken?
A centralised SDS workflow can make these questions easier to answer.
It can also help prevent a common operational problem: paying a contractor before the relevant status determination and documentation have been properly completed.
The CFO Takeaway
For UK IT and SaaS businesses, legally defensible SDS generation is not about producing more paperwork. It is about creating a reliable decision trail.
A strong process should:
Assess → Document → Determine → Generate SDS → Notify → Record → Monitor
The technology should make the process faster and more consistent, while the business retains appropriate oversight of the underlying determination.
For organisations with a growing contractor workforce, platforms that combine contractor management, IR35 workflows, status assessments and documentation can be worth evaluating as part of a broader compliance strategy.
Ready to Streamline Contractor Compliance?
If your UK technology business manages contractors through personal service companies, explore platforms that can help centralise IR35 assessments, SDS workflows, contractor documentation and payment processes.
Explore Deel for Contractor & IR35 Management →
Explore Multiplier for Contractor Compliance →
Before choosing a platform, review the current features, UK IR35 functionality, workflow controls and pricing against your organisation’s specific requirements.
Affiliate Disclosure:
This article may contain affiliate links. If you use a link and subsequently purchase a qualifying service, About Accounting UK may receive a commission at no additional cost to you. This does not change the editorial information provided in this article.
Compliance Note:
This article provides general business information and is not legal or tax advice. IR35 and employment-status decisions depend on the facts of each engagement. UK businesses should obtain appropriate professional advice where the correct status or tax treatment is uncertain.
What is a legally defensible Status Determination Statement?
A legally defensible SDS should state the employment-status determination, explain the reasons for the decision and demonstrate that the client took reasonable care when reaching its conclusion. For organisations within the relevant off-payroll rules, the SDS should be communicated to the worker and relevant contracting party, with records retained to support the determination.
What does HMRC mean by “reasonable care” for IR35?
HMRC says reasonable care means acting in a way that would be expected of a prudent and reasonable person in the client’s position when determining the worker’s status. Failure to take reasonable care can result in responsibility for deductions of tax and National Insurance and payment of the Apprenticeship Levy resting with the client.
When should an SDS be issued?
For an engagement within the relevant off-payroll rules, the client should communicate its determination through an SDS to the worker and the relevant organisation it contracts with. The SDS should contain the decision and reasons supporting it.
Can SDS generation be automated?
Technology can automate parts of the SDS workflow, such as collecting engagement information, recording assessments, generating documentation and distributing the SDS. However, automation does not transfer the client’s legal responsibility for taking reasonable care or ensuring the determination is accurate.