Merged R&D Tax Relief Solutions for UK Tech Scaleups
Optimize your innovation tax yield under HMRC’s unified R&D regime. Structure audit-proof technical evidence, protect software project claims, and secure up to a 20% gross taxable credit without exposing your business to enquiry friction.
What is the UK Merged R&D Tax Relief Scheme?
The new UK Merged R&D Tax Relief Scheme (Merged RDEC) is a single, unified tax incentive operating for accounting periods. Replacing the legacy dual SME and RDEC regimes, it awards an ‘above-the-line’ 20% gross expenditure credit to qualifying UK companies investing in scientific or technological advancements. The scheme establishes standardized rules around software/cloud spend, overseas subcontractor restrictions, and mandatory advance notifications.
Eligible IT Companies for UK Merged R&D Tax Relief.
UK limited companies liable for UK Corporation Tax-from early-stage tech startups to large enterprises-are eligible to claim the merged R&D Expenditure Credit (RDEC) if they carry out qualifying tech projects.
SaaS & Cloud Firm
Businesses developing custom microservices, multi-tenant architectures, or low-latency infrastructure.
AI & ML Developers
Firms engineering bespoke models, natural language processing (NLP), or complex data pipelines.
FinTech & InsurTech
Companies solving technological challenges around real-time transaction engines with complete compliance & security
Cybersecurity Firm
Developers building custom encryption methods, threat-detection engines, or zero-trust architectures.
IoT & Embedded Software
Firms writing firmware or hardware-software integration protocols for smart devices.
Software Consultancies
Software firms commissioned to perform R&D where they bear the commercial risk and compliance.
Key Drivers for Merged R&D Tax Relief
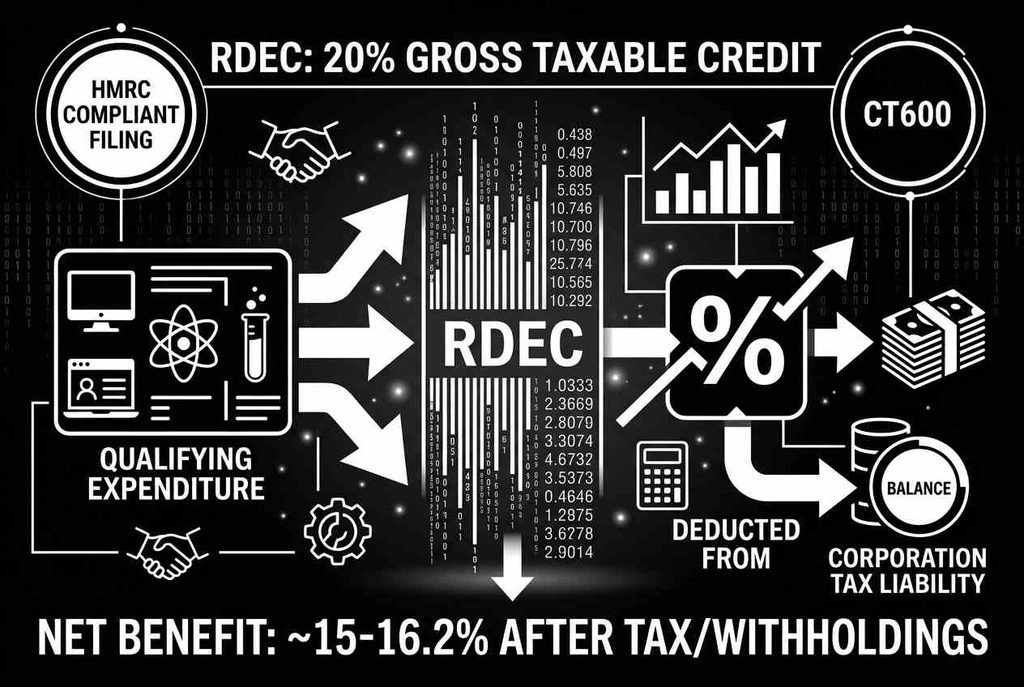
Navigating the 20% Merged R&D Expenditure Credit (RDEC)
A breakdown of “above-the-line” accounting, net-benefit math across corporate tax bands, and cash payout rules for loss-making firms.
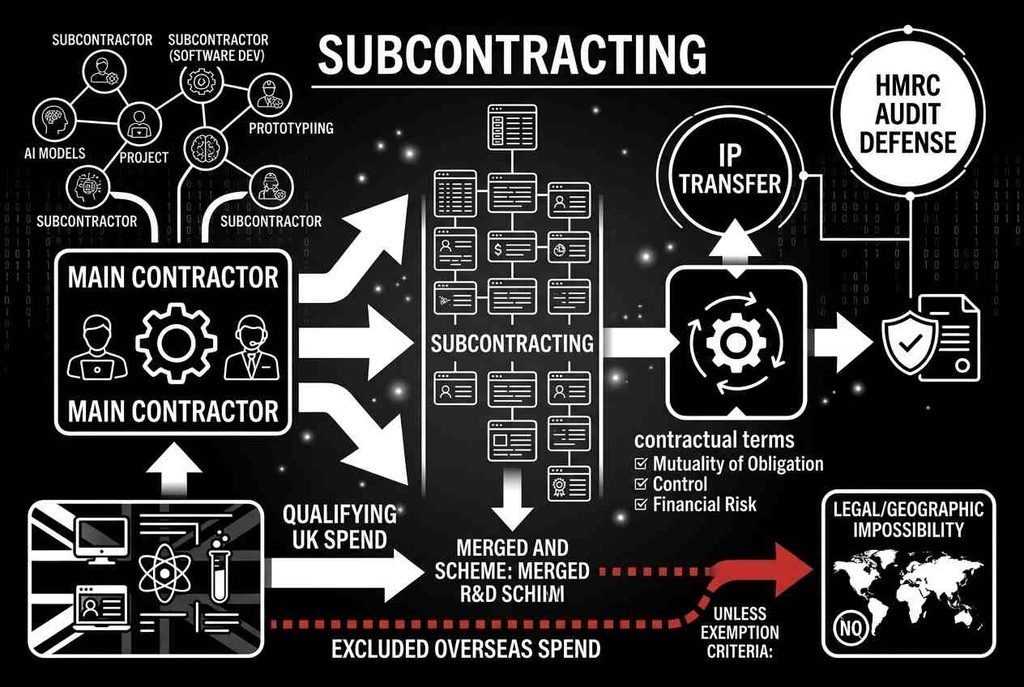
HMRC’s Subcontractor & Overseas Expenditure Rules
How to structure technical vendor contracts, navigate UK-conducted R&D requirements, and protect cross-border development claims.
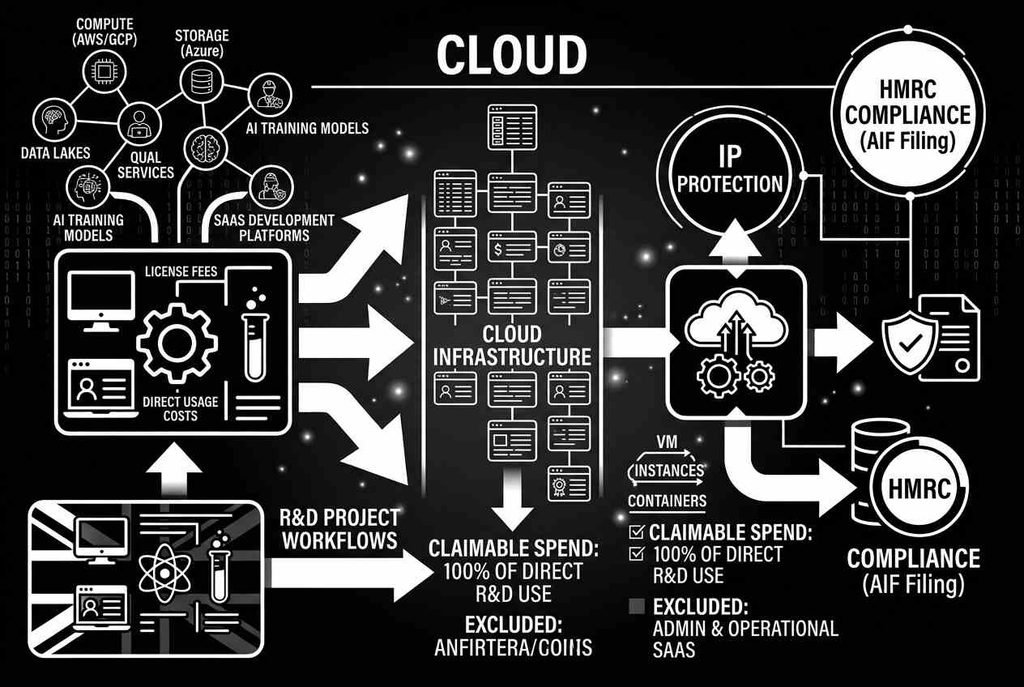
Qualifying Cloud Computing, Data Licenses & Software Spend.
Defining eligible SaaS infrastructure, data pipelines, and server costs under modern HMRC software development guidelines.
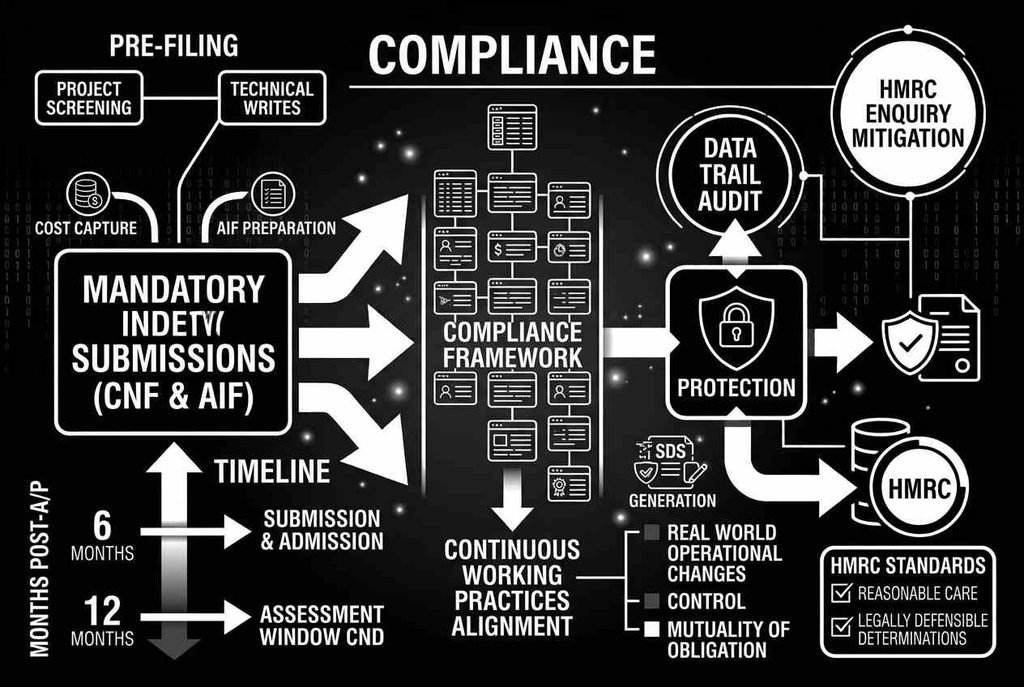
HMRC Compliance, AIF Filing & Pre-Notification Rules.
Master the mandatory Additional Information Form (AIF) and the 6-month Claim Notification Form (CNF) deadline to avoid claim disallowance.
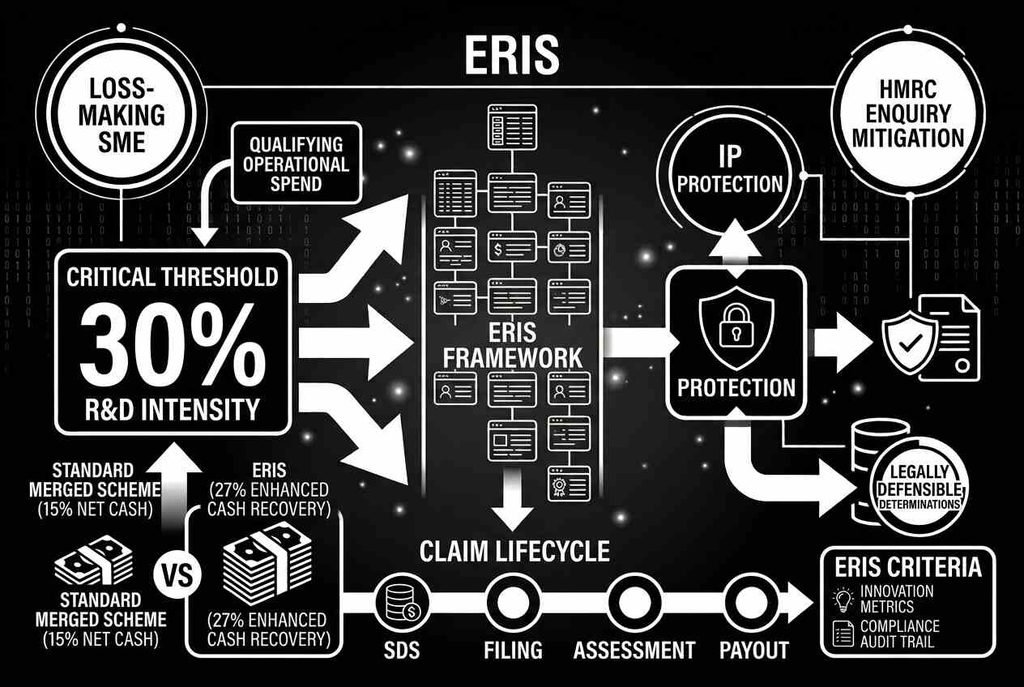
ERIS vs. Merged Scheme for R&D-Intensive Scaleups.
Strategic guidance for loss-making tech firms evaluating the 30% intensity threshold to maximize cash recovery.
Frequently Asked Questions (FAQ)
Merged R&D Tax Relief: Key Answers.
The merged UK R&D tax scheme replaces legacy RDEC and SME rules with a single 20% taxable credit. Find clear answers below on contractor claim rights, overseas spending limits, PAYE caps, and high-intensity ERIS eligibility.
Have any question? Write us. We are here.
Maximize Your R&D Yield with Complete HMRC Audit Defense.
Ensure your software expenditures and technical claims stand up to HMRC scrutiny under the current Merged Scheme rules.
Audit-Proof Your Merged R&D Claim Today.
Speak with our corporate tax advisory team to audit your software project spend, verify your ERIS intensity threshold, and compile robust technical evidence before filing your Additional Information Form.