UK Employer of Record Payroll: PAYE, National Insurance and Tax Explained
Payroll is one of the most important considerations when an international business hires employees in the United Kingdom.
A salary agreement is only one part of the employer’s financial responsibility. Businesses must also consider PAYE, National Insurance, workplace pensions and other applicable employment costs.
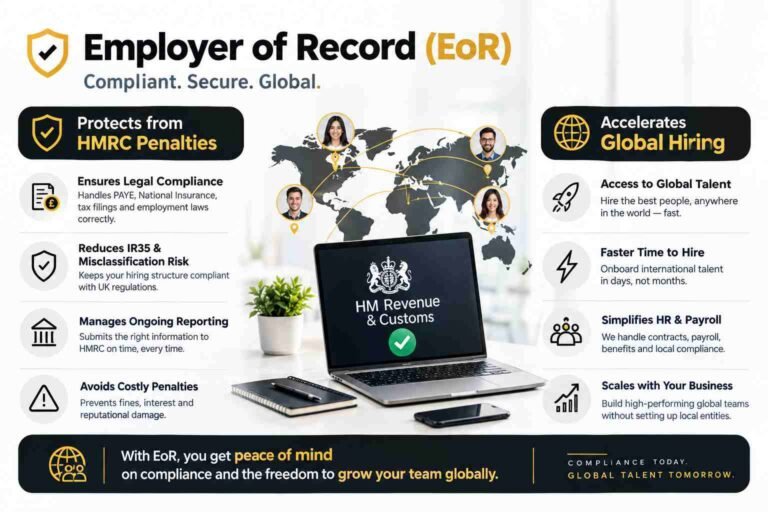
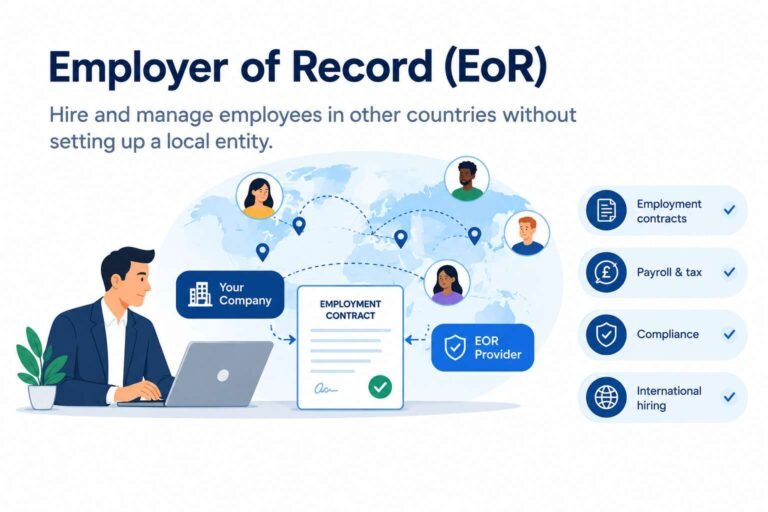
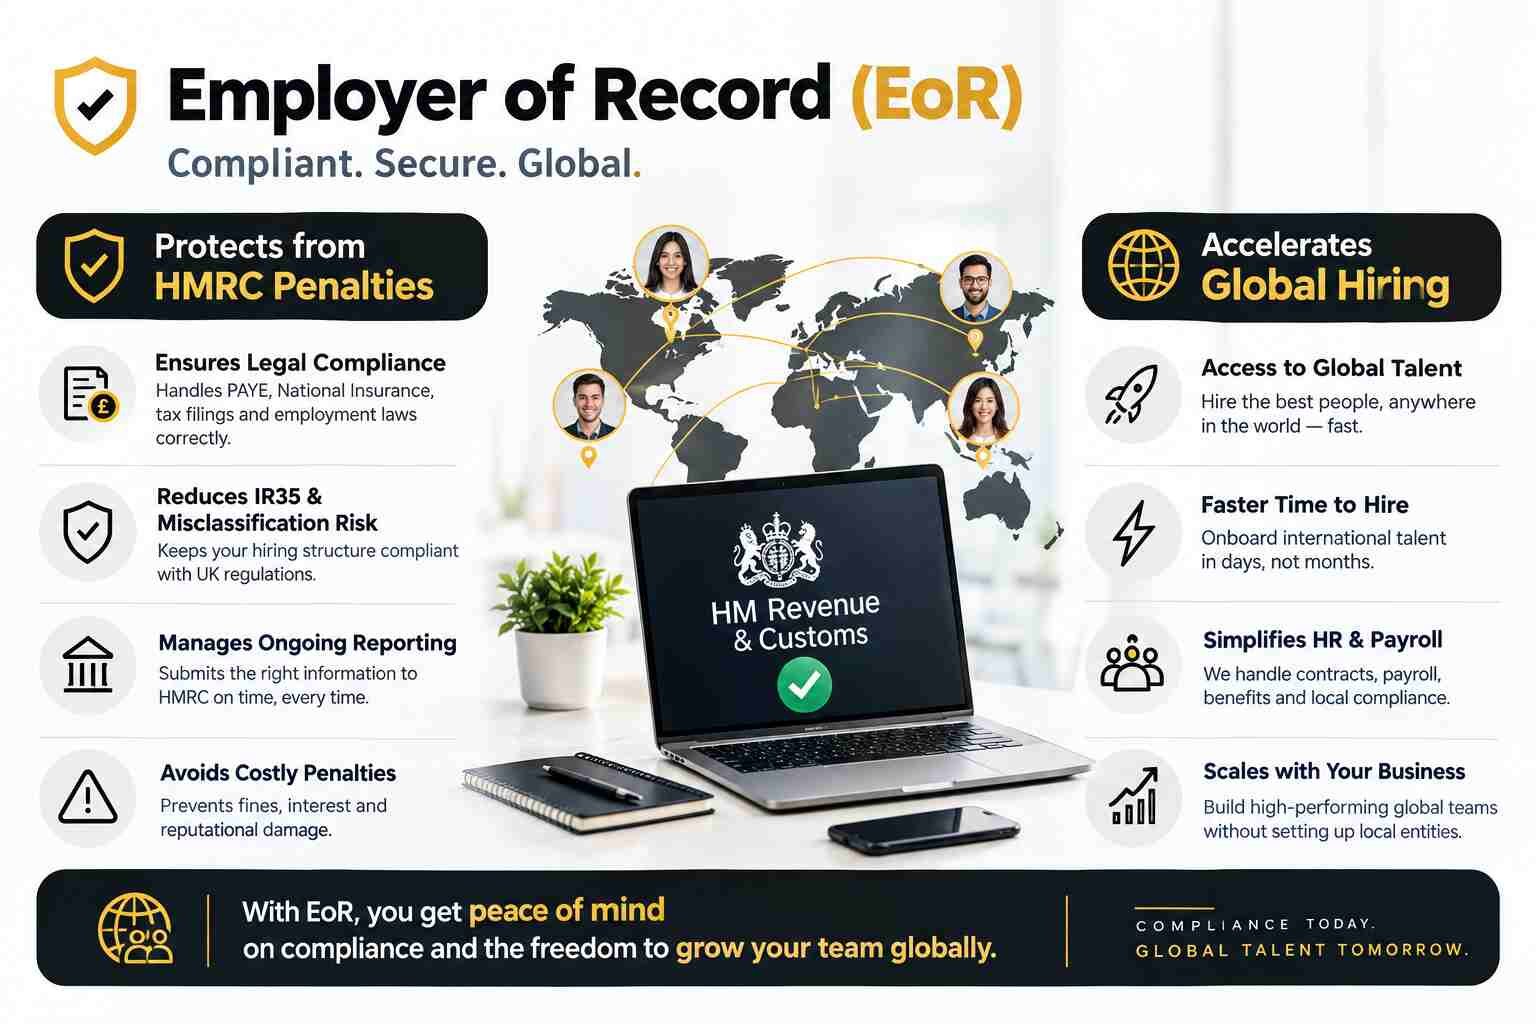
An Employer of Record (EoR) can help manage defined payroll and employment administration responsibilities. However, companies should understand what the arrangement covers and how the costs affect their financial planning.
What is UK EoR payroll?
UK EoR payroll is the process of administering employee pay through an Employer of Record arrangement.
Depending on the provider and agreement, the service may include:
- Salary processing
- PAYE administration
- National Insurance administration
- Statutory deductions
- Pension-related processes
- Payroll documentation
- Certain statutory payments
- Employee support
The exact scope varies between providers.
What is PAYE?
PAYE stands for Pay As You Earn.
It is the system used to collect Income Tax and National Insurance contributions through employment payroll, where applicable.
Employers must follow HMRC payroll requirements, including reporting relevant payroll information.
Under an EoR arrangement, the provider may operate the payroll process. Businesses should confirm which party is responsible for each obligation.
Employer National Insurance
Employer National Insurance is a cost that businesses need to consider when budgeting for UK employees.
For the 2026/27 tax year, HMRC’s published guidance lists a 15% employer Class 1 secondary contribution rate, subject to the applicable thresholds and rules.
The amount payable depends on earnings, employee category and other relevant circumstances. Use the current HMRC rates and thresholds when preparing a financial forecast.
Workplace pensions
Eligible UK employees may have workplace pension rights and employer contribution requirements.
The cost of pension contributions should be included in the total employment budget.
The specific contribution calculation depends on the employee’s circumstances and the applicable rules.
What does a CFO need to calculate?
A useful payroll budget includes:
Gross salary + employer National Insurance + pension contributions + benefits + EoR fees + other employment costs
For example, a company budgeting for a £60,000 annual salary should not automatically treat £60,000 as its complete employment cost.
The actual amount depends on statutory costs, benefits and the provider’s fee structure.
Payroll responsibilities under an EoR
Before signing an agreement, ask:
| Responsibility | Question |
|---|---|
| Payroll | Who processes monthly salary? |
| PAYE | Who manages relevant tax deductions and reporting? |
| National Insurance | Who administers employer and employee contributions? |
| Pension | Who handles workplace pension processes? |
| Benefits | Which benefits are included? |
| Corrections | How are payroll errors handled? |
| Reporting | What payroll information does the client receive? |
The contract should define the responsibilities clearly.
Common payroll mistakes
International companies may encounter problems when they:
- Use outdated statutory rates
- Exclude employer costs from forecasts
- Assume every benefit is included
- Fail to clarify payroll cut-off dates
- Ignore currency conversion costs
- Treat EoR fees as the complete cost of employment
- Do not review the contract’s responsibilities
A well-defined process can help reduce administrative confusion.
HMRC guidance and ongoing compliance
HMRC provides employer guidance on PAYE and National Insurance, including payroll reporting and relevant contribution requirements.
UK payroll rules can change, so businesses should verify current rates and obligations rather than rely on older articles or spreadsheets.
Final thoughts
Payroll is a core component of any UK hiring strategy.
An EoR may simplify administration by providing an established employment and payroll structure, but the business should understand the service scope and total cost before entering into an agreement.
About Accounting researches accounting and international employment topics to help businesses make informed decisions.
Affiliate disclosure: Some links may be affiliate links through which About Accounting receives a commission.
This article is general information and is not a substitute for professional payroll, tax or legal advice.